Data as of 23 September 2026
Every driver pays for the same barrel of oil. What they pay at the pump is a different story.
At the pumps, petrol can cost almost twice as much in Copenhagen as it does in Valletta, despite both countries buying crude on the same global market and in the same currency.
For traders, that matters. How crude prices pass through to fuel prices affects inflation. Inflation data affects central bank decisions, and central bank decisions move currencies. This year has been a live test of that chain.
Where crude stands now
Brent has had a volatile 2026. It was trading around $98.76 a barrel on 23 September, up 62.6% from the start of the year, when it traded at $60.75. The current 52-week range is roughly $58.72 to $126.41.
Geopolitics has been the main driver.
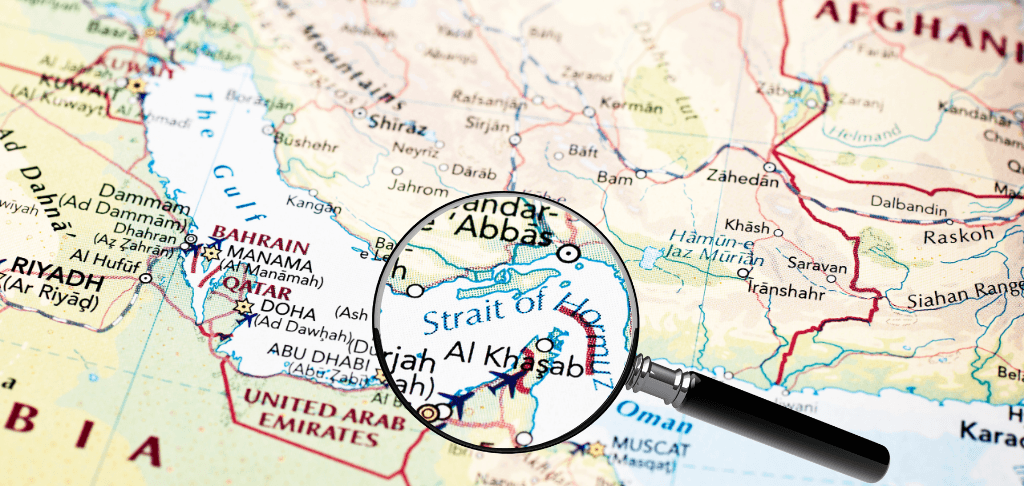
The Strait of Hormuz, one of the world’s most important oil shipping routes, has seen vessel traffic collapse since the Iran conflict began in late February. Before the conflict, roughly 20% of global oil supply moved through the strait. Recent maritime tracking data shows traffic at a fraction of normal levels. However, oil is still moving through the waterway, with Saudi Arabia shipping around 2.9 million barrels a day through it in recent days.
Prices have eased this week as the supply outlook improved. Saudi Arabia has resumed operations at its East-West pipeline, although pumping initially restarted at a reduced rate and full capacity is expected to take longer to restore. The pipeline provides an alternative route to the Red Sea, bypassing Hormuz. Reports that Iran was prepared to reopen the strait if the US reduced pressure also helped push prices lower.
The November Brent contract settled at $99.25 a barrel on 22 September, down $1.09 on the day, before prices moved lower again during trading on 23 September.
Same oil, very different pump prices
Here’s what drivers paid in a selection of countries, using official government and EU energy data. Prices include all taxes and are converted to US dollars per gallon at ECB reference rates. Because countries publish on different schedules, each row carries its own date.
| Country | Local price per litre | US$ per gallon | Period | Source |
| Denmark | €2.63 | $11.58 | Week of 7 Sep | EU Weekly Oil Bulletin |
| Netherlands | €2.47 | $10.85 | Week of 7 Sep | EU Weekly Oil Bulletin |
| Germany | €2.33 | $10.26 | Week of 7 Sep | EU Weekly Oil Bulletin |
| France | €2.11 | $9.30 | Week of 7 Sep | EU Weekly Oil Bulletin |
| United Kingdom | £1.68 | $8.59 | Week of 14 Sep | DESNZ |
| Cyprus | €1.63 | $7.18 | Week of 7 Sep | EU Weekly Oil Bulletin |
| Malta | €1.34 | $5.90 | Week of 7 Sep | EU Weekly Oil Bulletin |
| Brazil | R$6.53 | $4.84 | Week of 12 Sep | ANP |
| Canada | C$1.74 | $4.69 | August | Statistics Canada |
| United States | $1.14 | $4.32 | Week of 14 Sep | EIA |
| Japan | ¥170.0 | $4.16 | Week of 7 Sep | METI / ANRE |
| India (New Delhi) | ₹102.12 | $4.06 | 1 July | PPAC |
The US figure has already moved. The national average for regular gasoline reached $4.48 a gallon on 21 September, according to AAA data.
At the extreme low end are subsidized producers. Global retail petrol prices in July 2026 ranged from around $0.02 a liter in Libya to $3.24 in Israel. The enormous spread has far more to do with taxes, subsidies and domestic pricing policy than with the underlying price of crude.
A barrel isn’t a barrel of petrol.
This is the part that often gets lost when people compare crude prices with what they see at the pump.
Brent is crude oil, not finished gasoline. Before it reaches a driver’s tank, crude has to be transported, refined, and distributed. A refinery produces a mix of gasoline, diesel, jet fuel and other products, and each stage has its own costs and margins.
That is why a 10% move in Brent does not automatically produce a 10% move in petrol prices.
The pump price comes from several different markets, each adding its own cost between the oil field and the filling station.
Why the gap exists: tax
Crude is only one part of the pump price. Refining, distribution, retail margins and, above all, tax make up the rest.
The US is among the lowest-priced high-income markets, largely because fuel taxes are much lower than in most European countries. American drivers therefore tend to see a larger share of crude and fuel-market movements reflected in the price they pay.
Brent climbed about 63% between late December 2025 and mid-September. The EU’s average price for Euro-Super 95 rose less than half as fast, from €1.59 a liter to €2.06, or around 30%.
Tax is to blame for a lot of this gap. UK fuel duty is a flat 52.95p a liter, whether Brent is at $60 or $120. VAT does rise with the price, since it’s charged as a percentage, but the duty portion stays put. So when crude jumps, a big chunk of what drivers pay doesn’t move.
Europe’s pump prices have moved up this year, but they haven’t kept pace with Brent. The EU average for Euro-Super 95 was €2.06 a liter on 14 September, compared with €1.59 on 22 December 2025. That’s roughly a 30% increase. Over roughly the same period, Brent was up about 63%.
The reverse is true in low-tax markets. When fuel taxes account for a smaller part of the final price, movements in crude and refined fuel prices have more room to show up at the pump.
Why the gap exists: currency
Oil is priced in dollars. Anyone buying it in euros, pounds, or yen is also making a currency trade, whether they know it or not.
EUR/USD was holding near 1.16 after the ECB’s September decision. At that rate, a $98.76 barrel of Brent costs a European refiner about €85.
If EUR/USD fell to 1.05 with Brent unchanged, the same barrel would cost about €94. That’s a rise of more than 10% without any change in the oil market itself.
This works in reverse too. A strengthening local currency can soften a crude rally at the pump.
For traders, the currency move can make a noticeable difference to local fuel costs, even when Brent hasn’t changed.
Why pump prices lag
A delay usually exists between a move in crude and a change at the petrol station. Fuel bought at an earlier price is already in storage, and refiners also deal with their own costs and margins.
Economists and researchers have long described a pattern known as “rockets and feathers”, where retail fuel prices can rise faster than they fall.
There is another reason the relationship is messy. The price of refined gasoline is not simply crude plus a fixed markup. Traders often watch the crack spread, the difference between crude prices and the value of the refined products it produces. When crack spreads widen, refiners can make more from turning crude into gasoline and diesel, which can put additional pressure on wholesale fuel prices even if Brent itself isn’t moving much.
Refinery outages, seasonal demand, inventories, transportation costs and the relative value of gasoline and diesel can all affect the final price.
So even if Brent keeps falling on diplomacy, drivers shouldn’t expect an immediate matching drop at the pump.
From the pump to inflation to interest rates
Fuel prices feed directly into consumer price data, and this year they have been a major part of the inflation story.
United States. Headline CPI rose 0.4% in August and 3.4% over 12 months. The gasoline index rose 3.9% during the month and accounted for more than a third of the monthly increase.
The Fed raised its target federal funds rate by 25 basis points on 16 September, taking the range to 3.75% to 4%. Its statement said inflation remained elevated and noted that uncertainty remained high, including because of geopolitical developments. The decision came as energy prices were adding to the broader inflation problem, but the Fed did not describe the rate increase as a response to oil alone.
United Kingdom. UK CPI rose to 3.1% in August from 2.9% in July. Petrol rose by 9.1 pence a liter during the month to 161.3p, the highest level since November 2022. Motor fuel prices were up 23% from a year earlier. Transport, particularly motor fuels, contributed the most to the rise in inflation.
The Bank of England held Bank Rate at 3.75% on 17 September, but the vote was close. Six MPC members backed keeping rates unchanged while three voted for a rise to 4%. The Bank said the prolonged Middle East conflict had pushed crude and refined energy prices higher and more volatile than before the conflict, while warning that UK inflation was likely to rise further over the coming quarters.
Euro area. Eurozone inflation reached 3.2% in August, up from 2.9% in July. Energy inflation was 14.3%, up from 10.3% in July. Energy’s contribution to annual inflation jumped from 0.94 percentage points in July to 1.29 percentage points in August, more than accounting for the 0.3 percentage-point rise in headline inflation. Services contributed 1.43 points in August.
The ECB raised its three key interest rates by 25 basis points in September, taking the deposit facility rate to 2.50%. The ECB explicitly said the Middle East conflict was continuing to generate inflation pressures and that inflation was expected to remain above target for an extended period.
An energy shock can move from the commodity market into consumer prices and eventually into the monetary policy debate. That’s why commodity traders watch rate decisions and currency traders watch the oil market.
What can traders watch next?
Releases to watch before the next US CPI:
- EIA Weekly Petroleum Status Report: every Wednesday, covering US crude, gasoline, and other petroleum inventories.
- German flash inflation: 30 September.
- US PCE price index for August: 30 September at 8:30 a.m. EDT, the Fed’s preferred inflation measure.
- Eurozone flash inflation for September: 2 October.
- US CPI for September: Wednesday 14 October at 8:30 a.m. ET.
- Bank of England decision: 5 November, alongside the November Monetary Policy Report.
The next few releases will show how much of the oil move is reaching consumers, how quickly it gets there, and whether it starts showing up in broader inflation measures.
How traders approach oil and related markets
A CFD on Brent or WTI lets a trader take a position on crude prices without buying or storing any oil.
Because CFDs are traded on margin, a small deposit controls a much larger position, and a price move hits that deposit in full. This year’s oil market shows why that matters. Brent has swung between $58.72 and $126.41 over the past 52 weeks, and it fell around 3% in a single session on 22 September after one report about Iran and the Strait of Hormuz. A trader who hadn’t sized that position with room for moves like that could have lost a large share of their margin in a day.
Other traders watch currency pairs with an energy connection, such as USD/CAD, since Canada is a major oil exporter, or EUR/USD and USD/JPY, since the euro area and Japan are major energy importers.
The relationship is not fixed. A move in oil can matter to a currency, but interest-rate expectations, economic data, risk sentiment, and other factors can easily dominate the relationship at any given time.
What makes the current environment interesting is how many markets are being pulled into the same story.
A disruption in the Middle East can move Brent. Brent can move fuel prices. Fuel prices can move inflation. Inflation can change interest-rate expectations. And interest-rate expectations can move currencies.
The barrel at the start of that chain is the same one. The price at the other end can look very different depending on where you live.
CFDs are complex instruments and carry a high risk of rapid losses due to margin trading. Consider whether you understand how CFDs work and whether you can afford the risk of losing your money. This article is for educational purposes and is not investment advice.